The SBA homework for buying a business, done in minutes.
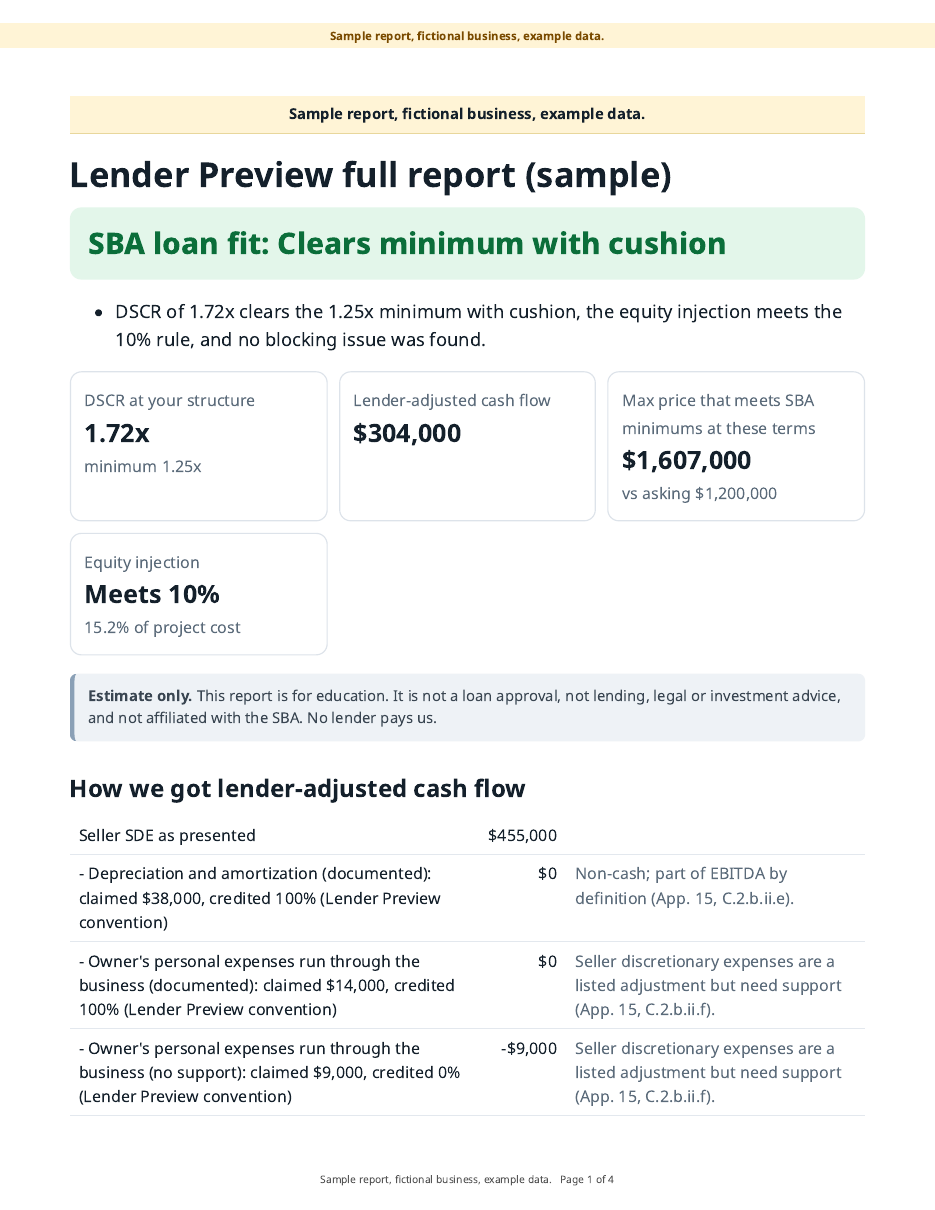
Sample report for a made-up deal. The numbers are illustrative only and not a prediction for your deal. Your report uses the figures you enter and the SBA rules in SOP 50 10 8.1. It is not a loan approval and not a lender's view.
Independent SBA 7(a) fit check for buyers: DSCR vs SBA minimums from five numbers. Full report: add-back adjustments, the equity test and the lenders with the most SBA 7(a) change-of-ownership loan approvals in your industry sector and state (statewide, and labelled, where fewer than 3 qualify).
Educational only. Not a lender, loan commitment, pre-approval, lender decision or advice. Lenders make their own credit decisions.
How it works
Enter your deal.
Start with five numbers in the free calculator, or fill in our CSV/XLSX template for the full report.
See how it measures against SBA minimums.
You get DSCR and a band: Clears minimum with cushion, Near minimum, or Below minimum. The full report shows every flag, with its SOP 50 10 8.1 citation where the SOP sets the rule.
Take it to your advisors.
Download the PDF and Excel to review with your CPA, attorney and lender, and check every figure with them before you rely on it.
How your deal measures against SBA minimums
- Clears minimum with cushion
- Near minimum
- Below minimum
Your DSCR band: Clears minimum with cushion / Near minimum / Below minimum. The cushion is our convention, not an SBA rule, and no band is a lender decision.
What we pull together for your deal
The current SBA rules
SOP 50 10 8.1, effective Oct 1, 2026: the 1.25x DSCR minimum (1.15x for a Business Expansion), the 10% equity rule, seller-note standby, valuation and QoE triggers. Every rule we encode.
Add-back judgments
Our rule-based estimate of which of the seller's add-backs a lender may keep or cut (a Lender Preview convention, not a lender decision), and what that does to cash flow, DSCR and the price you can pay.
The document list
The SBA eligibility and document checklist for a change-of-ownership loan, with the SOP section for each item.
The lenders who do these loans
Up to 10 lenders ranked by SBA 7(a) change-of-ownership loan approvals (cancelled loans excluded) in your 2-digit NAICS sector and the business's state, Oct 2023 to Jun 2026, from SBA FOIA data. Only lenders with at least one such approval are listed; where fewer than 3 qualify, we show the most active lenders statewide and say so. No lender pays to be listed.
Built for searchers, first-time acquirers, and the brokers and CPAs who advise them. It covers buying an existing business, not startup loans.
What changed on October 1, 2026
- Buying a business you don't own: at least 10% equity of total project cost, and it can't be reduced.
- A seller note counts toward that only if it's on full standby for the life of the loan, and standby notes plus outside minority investors can cover at most half. So at least 5% of project cost must come from unlimited sources, such as your own unborrowed cash or a gift.
- 1.25x DSCR (1.15x for a Business Expansion) on the last fiscal year or a two-year average. Projections can't be used to pass.
- A Quality of Earnings report at a purchase price of $3M and up.
Source: SBA SOP 50 10 8.1, Appendix 15. See every rule we encode.
Pricing
Free calculator. Lite $49 per deal (on screen). Full report $149 per deal or $349 for 3. Details
FAQ
What is Lender Preview?
An independent, educational SBA 7(a) loan fit check for people buying an existing business. It runs the numbers you enter against the SBA 7(a) rules in SOP 50 10 8.1 and shows how the deal measures against SBA minimums.
What isn't it?
It is not a loan approval, a loan offer or a commitment to lend. It is not lending, legal, tax, accounting or investment advice, and it is not an audit, attestation or valuation.
Is Lender Preview a lender?
No. Lender Preview is not a lender.
Does a lender review my deal?
No. No lender sees, reviews or approves your deal through Lender Preview. Every lender applies its own credit policy and makes its own decision.
Is the report a loan commitment?
No. It is not a loan commitment, a pre-approval or a lender decision.
Are you affiliated with the SBA or any lender?
No. Lender Preview is not affiliated with, endorsed by, or acting for the U.S. Small Business Administration or any lender, and no lender pays it any fee or referral payment.
Where does the lender list come from?
From public SBA 7(a) FOIA loan data (as of 2026-06-30). It shows up to 10 lenders: the lenders with the most SBA 7(a) change-of-ownership loan approvals in your industry sector and state. Only lenders with at least 1 such approval are listed, and the list is never padded. If fewer than 3 lenders had an SBA 7(a) change-of-ownership approval in your 2-digit NAICS sector and state, you see a statewide list instead, clearly labelled as a statewide list across all sectors, with a note saying fewer than 3 lenders qualified in your sector and state. It is ranked by change-of-ownership approvals, then change-of-ownership dollars approved. If the state has fewer than 3 too, the list is short and says so. No lender pays to be listed.
How much does it cost?
The calculator is free. Lender Preview report: one deal, $149. Lender Preview report: 3-pack (3 deals), $349. One-time payments, not subscriptions. Lender Preview Lite: one deal, $49 (on screen).
What is your refund policy?
Full refund within 14 days of purchase, capped at the price. To ask for one, reply to your purchase receipt.
What happens to my deal data?
Your numbers and uploaded files are processed in memory to build your report and are never stored. For paid reports we keep only a one-way code made from the deal name, sector and state in our payment processor's records, so re-running the same deal doesn't use another credit. Uploaded CSV/XLSX files are parsed in server memory, the fields are sent back to your browser for you to check, and the file is discarded. We do not train any model on your data. If you join the email list, your email address and the page you signed up on are stored with our email provider (ActiveCampaign) until you unsubscribe. Stripe handles payments and keeps your purchase record and receipt email; we never see your card number.
Your data
Your numbers and uploaded files are processed in memory to build your report and are never stored. For paid reports we keep only a one-way code made from the deal name, sector and state in our payment processor's records, so re-running the same deal doesn't use another credit.
Lender data: U.S. Small Business Administration, 7(a) FOIA loan data, file "FOIA - 7(a) (FY2020-Present)", as of 2026-06-30.